UAE Proptech Market Report: Trends, Growth and Forecast (2027-2033)
By Property Type (Residential, Commercial, Industrial & Logistics, Hospitality), By Solution (Software, Services), By Deployment (Cloud, On-Premise), By End User (Property Owners & Developers, Real Estate Agents & Brokerages, Facility & Property Managers, Property Investors & REITs), By Technology (IoT & Smart Sensor Networks, AI & Big Data Analytics, AR, VR & Digital Twins, Blockchain & Distributed Ledger Technology), By Region (Dubai, Abu Dhabi, Sharjah, Northern Emirates) ... Read more
|
Major Players
|
UAE Proptech Market Overview
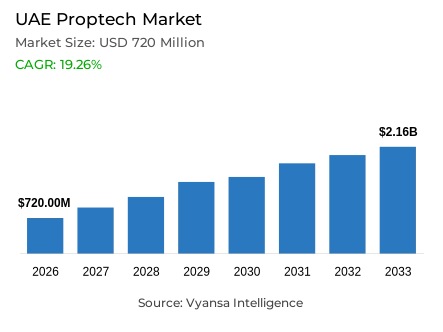
Proptech in the UAE refers to the digital platforms used across property discovery, brokerage, mortgage origination, transaction registration, fractional ownership and rental management, replacing manual, paper-based real estate processes with software and data-driven tools. Property buyers, tenants, investors, brokerages and government land registries use these platforms across residential and commercial real estate. The UAE proptech market is forecast to grow at a CAGR of 19.26% between 2027 and 2033.
Key Highlights of the UAE Proptech Market
- The UAE proptech market was valued at USD 0.72 billion in 2026 and is estimated at USD 0.75 billion in 2027, forecast to reach USD 2.16 billion by 2033.
- The market is forecast to expand at a compound annual growth rate of 19.26% between 2027 and 2033.
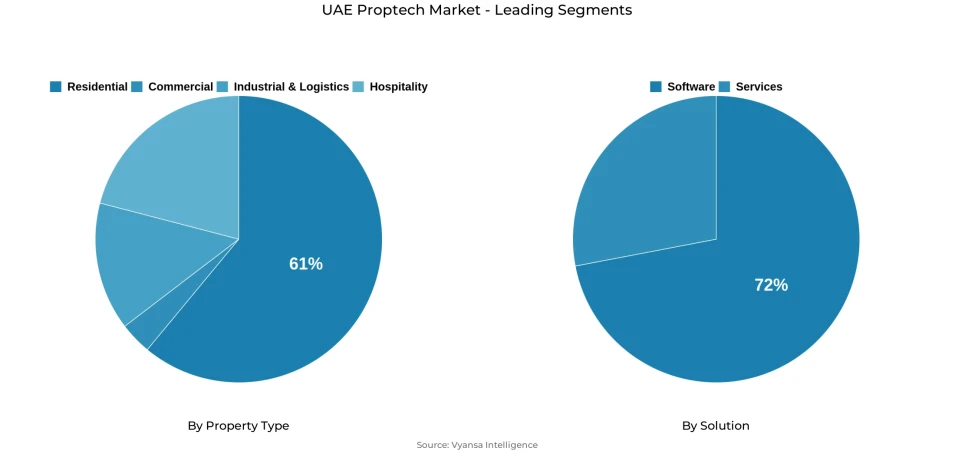
- By property type, residential led the market with a 61% share in 2026.
- Industrial & logistics is the fastest-growing property type, expanding at a CAGR of 15.83% between 2027 and 2033.
- By solution, software led the market with a 72% share in 2026.
- Services is the fastest-growing solution segment, expanding at a CAGR of 15.83% between 2027 and 2033.
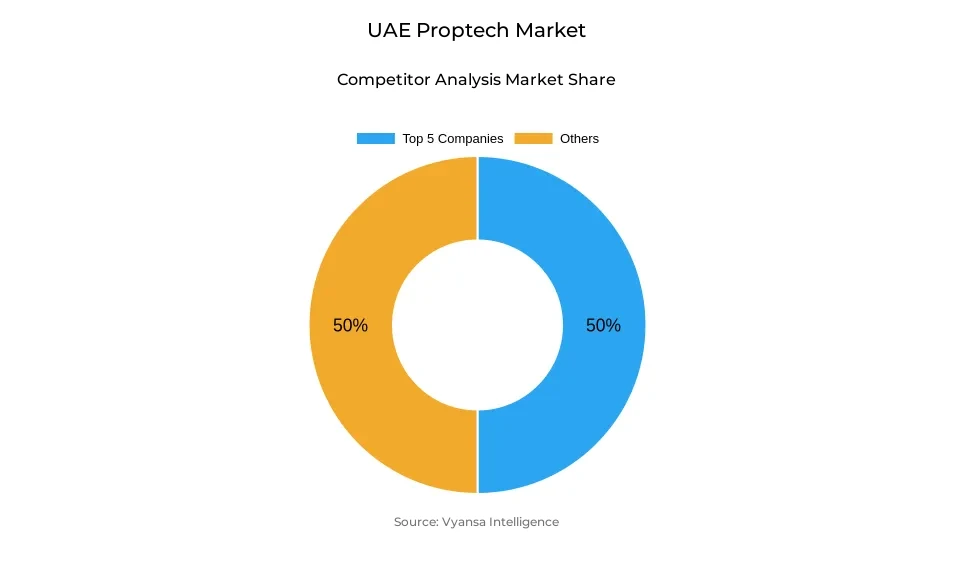
- The market is moderately consolidated, with the top five companies holding a combined 50% share in 2026.
The UAE proptech market is developing alongside one of the region's most active real estate sectors, providing technology companies with a large transaction and investor base to serve. Dubai recorded more than 270,000 real estate transactions worth approximately USD 249.7 billion during 2025, while total real estate procedures reached 3.11 million. The investor base increased to around 193,100, including approximately 129,600 new investors, strengthening demand for property discovery, valuation, brokerage, transaction management and portfolio solutions.
Technology is also becoming more deeply embedded across the property lifecycle. Dubai launched its dedicated proptech Hub to accelerate real estate innovation, with plans to support more than 200 proptech start-ups and scale-ups and attract more than USD 300 million in investment by 2030. Alongside this, the Dubai land department has introduced AI-supported rental valuation systems and fully digital property-sale services, expanding technology adoption beyond listing portals into registration, leasing, valuation, payments and investment decision-making.
However, ongoing geopolitical conflict across the Middle East is creating near-term pressure on the construction and property environment. Imported building-material costs in the UAE have increased by around 20–25% compared with pre-conflict levels as supply-chain and shipping disruptions raise procurement expenses. Dubai's off-plan transaction value also fell by more than 50% in June 2026 compared with February, indicating some weakening in investor-driven activity. Extended uncertainty could therefore affect selected project timelines, new launches and transaction-linked revenues for property platforms.
Despite these pressures, the underlying property market has continued to demonstrate considerable activity. Dubai real estate transactions reached approximately USD 68.62 billion in the first quarter of 2026, increasing 31% year over year, while investment value rose 22% to approximately USD 47.11 billion and the number of new investors increased 14% to 29,312. Through 2033, continued digitalisation of transactions, property records, leasing and investment services should support proptech adoption, although regional instability and construction-cost pressures could periodically moderate the pace of market expansion.
UAE Proptech Market Government Compliance
Government integration directly determines market access in several UAE proptech categories. In September 2026, Dubai land department launched its initial registration platform, integrating project registration, transaction registration and escrow account management within one digital workflow. For developers and proptech companies, this moves important transaction processes deeper into government-operated digital infrastructure and increases the value of platforms capable of integrating with these systems.
Tokenized property platforms face an additional qualification requirement. Dubai's virtual assets regulatory authority requires companies conducting regulated virtual-asset activities to obtain the appropriate approval before offering or facilitating such services. The authority specifically confirmed in February 2026 that firms promoting or facilitating tokenized real estate products must hold the necessary regulatory authorization.
The commercial effect is a higher entry threshold for fractional and tokenized property platforms. Companies already connected with Dubai Land Department and operating within the approved virtual-asset framework can move more easily from experimentation toward commercial transactions, while unlicensed entrants cannot simply launch equivalent investment products without regulatory integration.
UAE Proptech Market Driver
Digital Mortgage Platforms are Converting Property Demand into Completed Transactions
The UAE has a large pool of digitally generated property enquiries, but property discovery alone does not generate a completed demand when buyers must separately approach banks, compare mortgage products and coordinate documentation. Digital mortgage platforms address this gap by connecting property buyers with multiple lenders through one process, making financing part of the digital property journey rather than a separate offline stage.
The model has already reached meaningful scale. By 2026, Huspy was handling approximately 30% of mortgages in the UAE, demonstrating that technology-enabled mortgage origination has moved beyond a niche service and is participating directly in a substantial portion of financed home purchases. Its platform coordinates lender selection, applications and approvals while working across more than 20 banking relationships.
This strengthens proptech demand because financing platforms increase the proportion of property-search activity that can progress toward an actual transaction. As digital mortgage integration expands across developers, brokers and property portals, buyers can move more efficiently from property selection into financing and handover. The market therefore benefits not simply from more online property searches, but from technology capturing a greater share of the transaction process.
UAE Proptech Market Challenge
Cybersecurity and Data Protection Requirements are Increasing Platform Risk and Technology Costs
Proptech platforms increasingly combine personal identity information, financial documentation, property records, payment data and, in some cases, smart building information within connected cloud environments. The wider the digital property journey becomes, the greater the concentration of sensitive data within individual platforms and application interfaces. A security breach can therefore disrupt transactions while also exposing information belonging to buyers, tenants, investors, landlords and financial institutions.
The published UAE proptech research identified approximately 223,800 internet-facing digital assets in the country as potentially exposed to cyber threats. For proptech providers, this wider digital-risk environment is particularly relevant because their products increasingly depend on integrations between property databases, payment infrastructure, banks and government services rather than isolated software installations.
Providers must consequently invest in identity controls, secure data exchange, cloud security and continuing vulnerability management alongside product development. These requirements can raise the operating cost of connected proptech platforms and lengthen technology qualification for institutional clients. The challenge becomes more significant as the market moves toward integrated transaction systems, where disruption to one connection can affect several stages of the property journey.
UAE Proptech Market Trends
Artificial Intelligence is Moving into Real Estate Verification and Transaction Workflows
Artificial intelligence is becoming more deeply embedded in the UAE proptech market as platforms and government agencies move beyond basic search algorithms toward automated verification and decision support. The technology is particularly relevant where large volumes of listings and property records previously required manual checking, creating delays and inconsistencies across rapidly expanding digital marketplaces.
Dubai Land Department provides evidence of this transition at market scale. Its AI-enabled real estate advertising governance system, had reviewed more than 279,000 property advertisements, using automation to identify and correct listing issues. This demonstrates that artificial intelligence is already operating within the infrastructure surrounding major property portals rather than remaining limited to experimental consumer features.
As automated verification expands, private platforms can increasingly build property search, valuation and transaction tools around cleaner and more structured information. The commercial value of artificial intelligence should therefore shift from simply improving user recommendations toward improving data quality, reducing administrative work and accelerating property decisions. This creates stronger differentiation for platforms with access to verified transaction data and the capability to integrate it into real estate workflows.
UAE Proptech Market Opportunity
Abu Dhabi's Expanding Real Estate Market Creates a Second Major Proptech Growth Pool
Dubai currently contains the UAE's most mature proptech ecosystem, leaving Abu Dhabi as a substantial expansion opportunity for technology providers that have already established their products in the country. The opportunity is supported by growing transaction activity and the development of a separate digital real estate infrastructure, creating demand for locally integrated property portals, mortgage technology, rental platforms and transaction software.
Abu Dhabi recorded approximately USD 31.9 billion in real estate transactions during the first half of 2026. This provides sufficient transaction depth for proptech companies to build dedicated Abu Dhabi operations rather than treating the emirate as a smaller extension of their Dubai platforms. The expansion of investment zones and international participation further broadens the potential user base for digital property services.
Capturing this opportunity requires localization rather than simply replicating a Dubai product. Platforms need connections with Abu Dhabi's property data, local brokers, financial institutions and transaction infrastructure to provide a comparable digital customer journey. Companies that establish these integrations can diversify beyond Dubai while accessing a property market that is still developing its private proptech ecosystem around rapidly expanding digital government infrastructure.
Unlock Market Intelligence
Explore the market potential with our data-driven report
UAE Proptech Market Segmentation Analysis
By Property Type:
- Residential
- Commercial
- Industrial & Logistics
- Hospitality
Residential Property Leads UAE Proptech Adoption with 61% Share Across Digital Transaction and Management Platforms
Residential accounts for 61% of UAE proptech market demand in 2026 because it generates frequent interactions across property discovery, brokerage, mortgage financing, registration, rental management and investment. One residential buyer or tenant can interact with several digital services during the same property journey, giving the segment considerably more technology touchpoints than many larger but less frequently transacted commercial assets.
Residential demand is also supported by the UAE's large inflow of new and international property investors. Dubai alone added more than 129,000 new investors during 2025, expanding the potential user base for digital property discovery and transaction services. Industrial & Logistics is the fastest-growing Property Type at a 15.83% CAGR during 2027 to 2033. The segment benefits from growing requirements for digital leasing, asset management and facility management tools as logistics occupiers evaluate increasingly large property portfolios.
By Solution:
- Software
- Services
Software Commands UAE Proptech Spending with 72% Share Across Core Digital Real Estate Workflows
Software accounts for 72% of UAE proptech market spending in 2026 because property search, mortgage technology, digital transactions, valuation and investment platforms are fundamentally software-led services. Once deployed, these platforms can process additional users and property transactions without requiring service headcount to increase proportionally, supporting software's dominant position within the market.
AI is also increasing the functionality embedded directly within software platforms. Property Finder's Home Valuation feature, for example, uses machine learning together with verified property data to provide current valuations, six-month value projections and rental-yield insights. This illustrates how proptech software is expanding beyond property discovery into decision support and predictive analytics. Services are the fastest-growing Solution segment at a 15.83% CAGR during 2027 to 2033 as companies require greater implementation, integration and advisory support to connect property platforms with government, banking, and transaction systems.
Unlock Market Intelligence
Explore the market potential with our data-driven report
UAE Proptech Market Competitive Landscape
The UAE proptech market is moderately consolidated, with the top five companies holding a combined 50% share in 2026. Propertyfinder FZ-LLC and Dubizzle Group Holdings Limited lead property discovery and portal distribution, Huspy Mortgage Broker FZE leads mortgage technology, and Stake Properties Limited and PRYPCO Real Estate LLC lead fractional and tokenized property investment. The remaining share is distributed across a longer tail of rental-fintech, valuation and brokerage-technology providers competing for adjacent segments of the same transaction stack.
Key Companies in the UAE Proptech Market
- Propertyfinder FZ-LLC
- Dubizzle Group Holdings Limited
- Huspy Mortgage Broker FZE / Home Matters Real Estate Broker LLC
- Stake Properties Limited
- PRYPCO Real Estate LLC
- Smart Crowd
- Keyper
- Silkhaus
- REELLY Tech
- Nomad Homes
Company Profiling
The following profiles cover the five leading companies shaping product development, distribution and competitive positioning across the UAE proptech market.
Propertyfinder FZ-LLC: Property Finder operates one of the UAE's leading property-search and digital real estate platforms, connecting buyers and tenants with residential and commercial listings while expanding into valuation and investment services. In January 2026, the company secured USD 170 million in new investment following a USD 525 million equity investment in 2025. It also expanded its technology offering through AI-powered property valuation and deeper integration with fractional-investment services.
Dubizzle Group Holdings Limited: Dubizzle Group participates primarily through Bayut and dubizzle, giving it a large digital property-discovery and classifieds presence across the UAE. The group is expanding beyond listings through adjacent rental and transaction services. By April 2026, the rental-guarantee product integrated with its portals covered more than 95,000 rental units, demonstrating how the company is using its existing property audience to expand into additional transaction-related services.
Huspy Mortgage Broker FZE: Huspy operates a technology-enabled mortgage and real estate platform connecting property buyers with lenders and financing support. By May 2026, the company stated that it was powering around 25% of UAE mortgages and serving more than 12,000 homeowners. In May 2026, Huspy also partnered with Dubai Holding Real Estate to provide integrated mortgage and handover financing support to customers across major residential developments.
Stake Properties Limited: Stake provides digital fractional property investment and is expanding into broader liquidity and ownership services. In April 2026, Stake partnered with ACE & Company to develop secondary-transfer capabilities for fractional real estate investments in the UAE, addressing one of the major limitations of private fractional ownership by improving potential investor liquidity.
PRYPCO Real Estate LLC: PRYPCO participates through digital property investment and the PRYPCO Mint tokenized real estate platform operating within Dubai Land Department's regulated tokenization initiative. During 2026, the platform moved into secondary-market trading, allowing investors to buy and sell tokenized ownership interests through its digital marketplace. This positions PRYPCO at the center of Dubai's transition from fractional-property pilots toward a functioning digital ownership ecosystem.
Recent Developments in the UAE Proptech Market
- September 2026: Dubai Land Department launched the Initial Registration platform, integrating project registration, transaction registration and escrow management within one digital process supported by automation and AI. The development strengthens the government digital infrastructure on which private proptech platforms increasingly depend.
- July 2026: PRYPCO Mint reduced the entry level for its tokenized real estate platform to approximately USD 272, widening access to fractional property investment. The platform also operates a secondary marketplace, allowing investors to trade qualifying property tokens digitally.
- January 2026: Property Finder secured USD 170 million in new investment led by Mubadala alongside other investors. The funding followed a USD 525 million investment completed in 2025 and provides additional capital for expansion beyond conventional property listings into a broader transaction and technology ecosystem.
Frequently Asked Questions
Related Report
- Market Segmentation
- Research Scope
- Research Methodology
- Definitions and Assumptions
- Executive Summary
- UAE Proptech Market Policies, Regulations, and Standards
- UAE Proptech Market Dynamics
- Growth Factors
- Challenges
- Trends
- Opportunities
- UAE Proptech Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Property Type
- Residential- Market Insights and Forecast 2023-2033, USD Million
- Commercial- Market Insights and Forecast 2023-2033, USD Million
- Industrial & Logistics- Market Insights and Forecast 2023-2033, USD Million
- Hospitality- Market Insights and Forecast 2023-2033, USD Million
- By Solution
- Software- Market Insights and Forecast 2023-2033, USD Million
- Services- Market Insights and Forecast 2023-2033, USD Million
- By Deployment
- Cloud- Market Insights and Forecast 2023-2033, USD Million
- On-Premise- Market Insights and Forecast 2023-2033, USD Million
- By End User
- Property Owners & Developers- Market Insights and Forecast 2023-2033, USD Million
- Real Estate Agents & Brokerages- Market Insights and Forecast 2023-2033, USD Million
- Facility & Property Managers- Market Insights and Forecast 2023-2033, USD Million
- Property Investors & REITs- Market Insights and Forecast 2023-2033, USD Million
- By Technology
- IoT & Smart Sensor Networks- Market Insights and Forecast 2023-2033, USD Million
- AI & Big Data Analytics- Market Insights and Forecast 2023-2033, USD Million
- AR, VR & Digital Twins- Market Insights and Forecast 2023-2033, USD Million
- Blockchain & Distributed Ledger Technology- Market Insights and Forecast 2023-2033, USD Million
- By Region
- Dubai- Market Insights and Forecast 2023-2033, USD Million
- Abu Dhabi- Market Insights and Forecast 2023-2033, USD Million
- Sharjah- Market Insights and Forecast 2023-2033, USD Million
- Northern Emirates- Market Insights and Forecast 2023-2033, USD Million
- By Competitors
- Competition Characteristics
- Market Share & Analysis
- By Property Type
- Market Size & Growth Outlook
- UAE Residential Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Solution- Market Insights and Forecast 2023-2033, USD Million
- By Deployment- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Region- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- UAE Commercial Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Solution- Market Insights and Forecast 2023-2033, USD Million
- By Deployment- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Region- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- UAE Industrial & Logistics Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Solution- Market Insights and Forecast 2023-2033, USD Million
- By Deployment- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Region- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- UAE Hospitality Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Solution- Market Insights and Forecast 2023-2033, USD Million
- By Deployment- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Region- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Competitive Outlook
- Company Profiles
- Propertyfinder FZ-LLC
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Dubizzle Group Holdings Limited
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Huspy Technology FZ-LLC
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Stake Properties Limited
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- PRYPCO Real Estate LLC
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Smart Crowd Limited
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Keyper Technologies FZ-LLC
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Silkhaus Vacation Homes LLC
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- REELLY Tech Ltd
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Nomad Homes
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Propertyfinder FZ-LLC
- Company Profiles
- Disclaimer
| Segment | Sub-Segment |
|---|---|
| By Property Type |
|
| By Solution |
|
| By Deployment |
|
| By End User |
|
| By Technology |
|
| By Region |
|
Research Methodology
This study followed a structured approach comprising four key phases to assess the size and scope of the electro-oxidation market. The process began with thorough secondary research to collect data on the target market, related markets, and broader industry context. These findings, along with preliminary assumptions and estimates, were then validated through extensive primary research involving industry experts from across the value chain. To calculate the overall market size, both top-down and bottom-up methodologies were employed. Finally, market segmentation and data triangulation techniques were applied to refine and validate segment-level estimations.
Secondary Research
The secondary research phase involved gathering data from a wide range of credible and published sources. This step helped in identifying industry trends, defining market segmentation, and understanding the market landscape and value chain.
Sources consulted during this phase included:
- Company annual reports, investor presentations, and press releases
- Industry white papers and certified publications
- Trade directories and market-recognized databases
- Articles from authoritative authors and reputable journals
- Gold and silver standard websites
Secondary research was critical in mapping out the industry's value chain and monetary flow, identifying key market segments, understanding regional variations, and tracking significant industry developments.
Other key sources:
- Financial disclosures
- Industry associations and trade bodies
- News outlets and business magazines
- Academic journals and research studies
- Paid industry databases
Primary Research
To validate secondary data and gain deeper market insights, primary research was conducted with key stakeholders across both the supply and demand sides of the market.
On the demand side, participants included decision-makers and influencers from end-user industries—such as CIOs, CTOs, and CSOs—who provided first-hand perspectives on market needs, product usage, and future expectations.
On the supply side, interviews were conducted with manufacturers, industry associations, and institutional participants to gather insights into current offerings, product pipelines, and market challenges.
Primary interviews provided critical inputs such as:
- Market size and revenue data
- Product and service breakdowns
- Market forecasts
- Regional and application-specific trends
Stakeholders consulted included:
- Leading OEM and solution providers
- Channel and distribution partners
- End users across various applications
- Independent consultants and industry specialists
Market Size Estimation and Data Triangulation
- Identifying Key Market Participants (Secondary Research)
- Goal: To identify the major players or companies in the target market. This typically involves using publicly available data sources such as industry reports, market research publications, and financial statements of companies.
- Tools: Reports from firms like Gartner, Forrester, Euromonitor, Statista, IBISWorld, and others. Public financial statements, news articles, and press releases from top market players.
- Extracting Earnings of Key Market Participants
- Goal: To estimate the earnings generated from the product or service being analyzed. This step helps in understanding the revenue potential of each market player in a specific geography.
- Methods: Earnings data can be gathered from:
- Publicly available financial reports (for listed companies).
- Interviews and primary data sources from professionals, such as Directors, VPs, SVPs, etc. This is especially useful for understanding more nuanced, internal data that isn't publicly disclosed.
- Annual reports and investor presentations of key players.
- Data Collation and Development of a Relevant Data Model
- Goal: To collate inputs from both primary and secondary sources into a structured, data-driven model for market estimation. This model will incorporate key market KPIs and any independent variables relevant to the market.
- Key KPIs: These could include:
- Market size, growth rate, and demand drivers.
- Industry-specific metrics like market share, average revenue per customer (ARPC), or average deal size.
- External variables, such as economic growth rates, inflation rates, or commodity prices, that could affect the market.
- Data Modeling: Based on this data, the market forecasts are developed for the next 5 years. A combination of trend analysis, scenario modeling, and statistical regression might be used to generate projections.
- Scenario Analysis
- Goal: To test different assumptions and validate how sensitive the market is to changes in key variables (e.g., market demand, regulatory changes, technological disruptions).
- Types of Scenarios:
- Base Case: Based on current assumptions and historical data.
- Best-Case Scenario: Assuming favorable market conditions, regulatory environments, and technological advancements.
- Worst-Case Scenario: Accounting for adverse factors, such as economic downturns, stricter regulations, or unexpected disruptions.