Global Hi-tech Medical Devices Market Report: Trends, Growth and Forecast (2027-2033)
By Product Type (Diagnostic Imaging Equipment, Cardiovascular Devices, In-Vitro Diagnostic Devices, Surgical Equipment and Robotic Systems, Orthopedic Devices, Neurology Devices, Ophthalmic Devices, Dental Devices, Diabetes Care Devices, Anesthesia and Respiratory Devices, Nephrology and Urology Devices, ENT Devices, Monitoring and Digital Health Devices, Others), By Technology (AI-Enabled Medical Devices, Robotics-Assisted Medical Devices, IoT / Connected Medical Devices, Wearable Medical Devices, Minimally Invasive Systems, Imaging and Visualization Systems), By Application (Diagnosis, Monitoring, Therapeutics / Treatment, Surgical Procedures, Rehabilitation), By End User (Hospitals and Clinics, Diagnostic and Imaging Centers, Ambulatory Surgical Centers, Research and Academic Institutes, Home Care Settings), By Region (North America, South America, Europe, Middle East & Africa, Asia Pacific) ... Read more
|
Major Players
|
Hi-tech Medical Devices Market Overview
Hi-tech medical devices are imaging scanners, in-vitro diagnostic analyzers, robotic surgical systems, connected sensors and artificial intelligence (AI) software that help clinicians diagnose, treat and monitor patients. Hospitals, diagnostic centers, surgery centers, research institutes and home care users consume them across diagnosis, monitoring, therapy, surgery and rehabilitation. The Hi-tech medical devices market is forecast to grow at a compound annual growth rate (CAGR) of 5.80% between 2027 and 2033.
Key Highlights of the Hi-tech Medical Devices Market
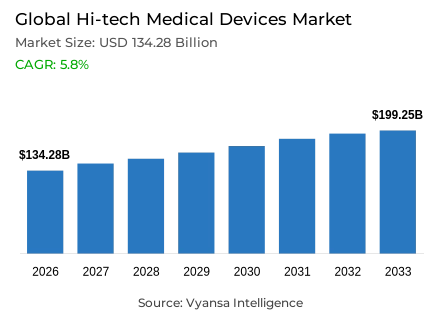
- The Hi-tech medical devices market was valued at USD 134.28 billion in 2026, the market is estimated at USD 142.06 billion in 2027 and is projected to reach USD 199.25 billion by 2033.
- The market is forecast to expand at an overall CAGR of 5.80% across the 2027 to 2033 forecast period.
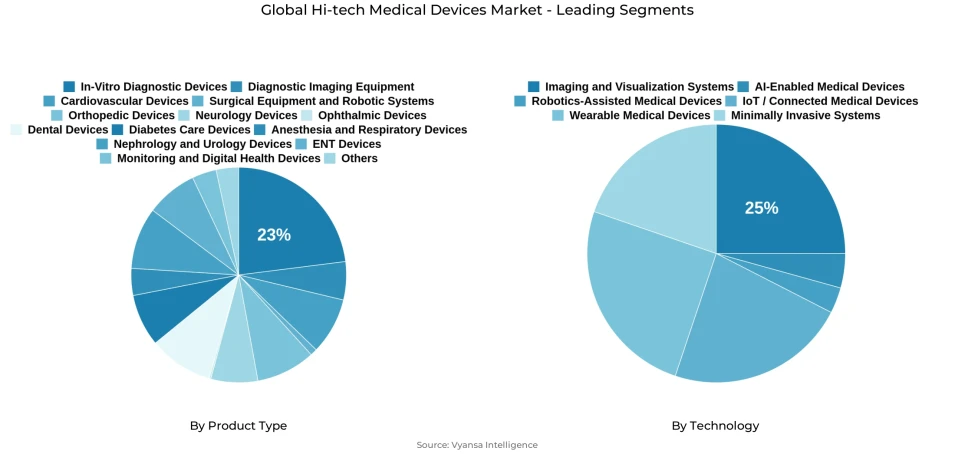
- In-Vitro diagnostic devices led the product type segmentation with a 23% share in 2026.
- Monitoring and digital health devices are the fastest-growing product and device type segment, expanding at a CAGR of 19.20% across the 2027 to 2033 forecast period.
- Imaging and visualization systems led the technology segmentation with a 25% share in 2026.
- AI-Enabled Medical Devices is the fastest-growing technology segment, expanding at a CAGR of 19.85% across the 2027 to 2033 forecast period.
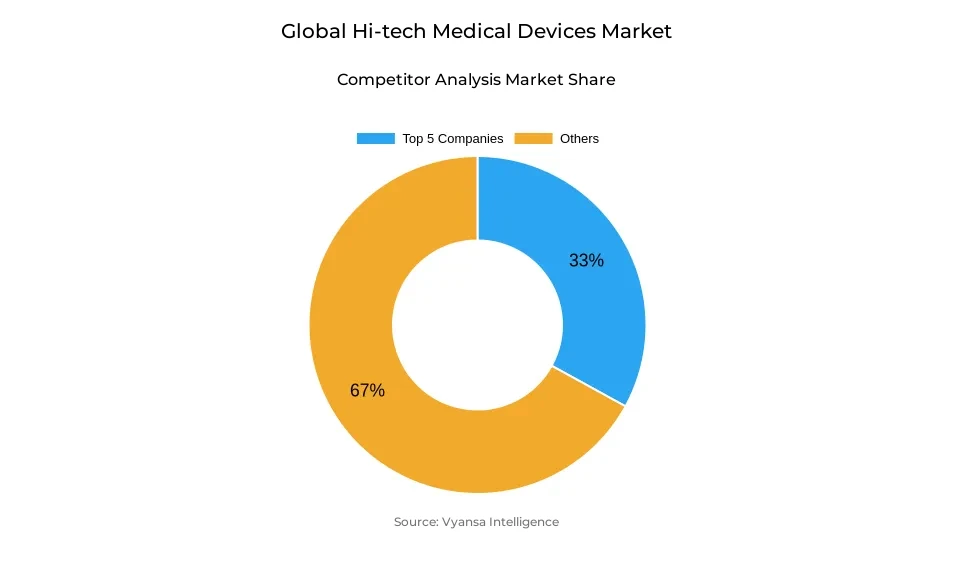
- The market is moderately fragmented, with the top five companies together holding a combined 33% share of total revenue in 2026.
Healthcare systems worldwide are managing rising volumes of testing, imaging, treatment, and continuing patient monitoring. The International Diabetes Federation estimated that 589 million adults were living with diabetes in 2024 and expects the number to reach 853 million by 2050. This enlarges the population requiring recurring diagnostic tests, glucose monitoring, cardiovascular assessment and complication screening, creating demand across laboratory systems, connected sensors and imaging equipment.
Demand is also moving beyond standalone equipment. Hospitals increasingly evaluate whether scanners, analyzers and surgical systems can connect with clinical software, automate repetitive work and remain supported throughout their operating lives. In the United States, national health expenditure is projected to grow by an average of 5.8% annually between 2024 and 2033. Although this spending covers the wider healthcare system, it gives providers a larger funding base from which to replace equipment and adopt technologies that improve clinical capacity.
Future demand should therefore come from both equipment replacements in established health systems and first-time deployment in under-equipped facilities. Suppliers will need to combine dependable hardware with clinical software, maintenance and training rather than compete only through device specifications. Through the forecast period, companies that help providers process more examinations, tests and procedures without proportionally increasing staffing will be best positioned to secure continuing adoption.
Hi-tech Medical Devices Market Drivers
Public Hospital Modernization Creates Scheduled Equipment Demand
Government infrastructure programs convert general healthcare needs into funded orders for diagnostic, monitoring and treatment equipment. Germany made its hospital transformation fund available from January 2026, with up to approximately USD 58 billion allocated through 2035 for modernizing hospital structures. The program gives hospitals a long investment period in which to reorganise clinical services and replace the equipment needed to deliver them.
India is expanding a different part of the healthcare system. By March 2026, its national health infrastructure program had approved 744 integrated public health laboratories alongside district and local health facilities. These laboratories require analyzers, sample-processing equipment and supporting digital systems before they can operate at their intended capacity.
Such programs matter because equipment purchases are supported by defined facilities, funding periods and implementation targets. They also generate demand after installation through maintenance, calibration, software support and consumables. Through the forecast period, public hospital modernization should remain an important source of orders for suppliers able to meet tender requirements and support equipment beyond major urban hospitals.
Hi-tech Medical Devices Market Challenges
European Certification Requirements Delay Product Entry
Manufacturers seeking to sell medical devices in Europe must satisfy extensive clinical, quality and post-market requirements under the medical device and in-vitro diagnostic frameworks. Certification commonly requires assessment by an authorized third party, making market entry dependent on both the manufacturer’s documentation and the availability of external assessment capacity.
The European Commission acknowledged these pressures in December 2025 when it proposed simplifying the existing framework. The proposed changes include greater digitalisation, clearer assessment timelines and more proportionate requirements for certain established devices. However, the proposal does not immediately remove the cost and uncertainty faced by products already moving through certification.
Long or unpredictable reviews can postpone launches, delay hospital access to upgraded products and increase the cost of maintaining older certified models. Large manufacturers can distribute these expenses across wider portfolios, while smaller device and software developers may delay European entry. Until the proposed changes are implemented, certification pressure will continue to favor companies with established European portfolios and dedicated regulatory resources.
Recent Trends in the Hi-tech Medical Devices Market
Value-Based Procurement Changes Supplier Selection
Medical-device procurement is gradually moving beyond comparisons based primarily on purchase price. In June 2026, the United Kingdom introduced national value-based procurement guidance for medical technology. The guidance gives buyers standard questions and assessment criteria covering productivity, patient outcomes, staff experience, environmental performance and supply-chain resilience.
This approach changes the information suppliers need to present in a tender. A manufacturer must demonstrate how its device affects workflow, maintenance requirements, clinical outcomes and total operating cost rather than relying only on equipment specifications. Connected systems that document utilization, downtime and procedural performance can provide stronger evidence than devices without comparable operating data.
The trend favors suppliers capable of supporting equipment throughout its usable life and proving measurable value after installation. As similar procurement methods spread, product development and sales strategies will increasingly need to address hospital-wide performance, not only the immediate function of the device.
Multi-Indication AI Expands Imaging Workflows
Medical AI is moving from tools developed for one clinical finding toward models that can assess multiple conditions within a shared workflow. This reduces the need for hospitals to integrate and manage several separate applications and makes AI more relevant when imaging equipment and radiology software are procured together.
In January 2026, Aidoc received FDA clearance for an abdominal CT model covering 14 acute indications. The company reported mean sensitivity of 97% and mean specificity of 98%. A single model capable of identifying several urgent findings can help radiology departments priorities time-sensitive studies without maintaining a different triage application for every condition.
The commercial value depends on integration with imaging archives, reporting systems and clinical review processes. Suppliers that package validated models with deployment support and continuing updates can create recurring software demand around installed scanners. This is gradually making AI capability part of the broader purchasing decision for imaging platforms.
Hi-tech Medical Devices Market Future Opportunities
Portable Imaging Can Extend Diagnostics Beyond Major Hospitals
Access to imaging remains uneven because conventional systems require substantial capital, dedicated rooms and trained operators. In May 2025, the World Health Assembly adopted a resolution calling for greater access to affordable medical imaging and continued investment in equipment, maintenance, infrastructure and workforce training. The resolution gives governments a basis for incorporating imaging capacity into national health plans.
Portable systems can address this requirement with lower installation needs and greater flexibility across primary-care, emergency and rural settings. In March 2026, Butterfly Network received FDA clearance for an AI-enabled ultrasound tool that estimates gestational age in less than two minutes without requiring conventional fetal measurements or specialist image interpretation. The technology had already been deployed in Malawi and Uganda.
The opportunity extends beyond selling smaller equipment. Leading companies can combine portable devices with guided scanning, remote review, training and service contracts designed for facilities without specialist imaging teams. This can open demand among healthcare providers that could not economically operate conventional systems.
Unlock Market Intelligence
Explore the market potential with our data-driven report
Hi-tech Medical Devices Market Segmentation Analysis
By Product Type:
- Diagnostic Imaging Equipment
- Cardiovascular Devices
- In-Vitro Diagnostic Devices
- Surgical Equipment and Robotic Systems
- Orthopedic Devices
- Neurology Devices
- Ophthalmic Devices
- Dental Devices
- Diabetes Care Devices
- Anesthesia and Respiratory Devices
- Nephrology and Urology Devices
- ENT Devices
- Monitoring and Digital Health Devices
- Others
Recurring Laboratory Testing Keeps In-Vitro Diagnostic Devices Ahead at 23%
In-Vitro Diagnostic Devices held the dominant 22.8% share in 2026. The segment benefits from recurring testing because installed analysers require assays, reagents and other consumables for each patient sample. In July 2026, Roche received FDA clearance for its cobas BV/CV assay, which identifies bacterial vaginosis and candida vaginitis from one vaginal swab on existing cobas laboratory systems. Expanding the test menu available on installed analysers supports continuing utilisation and strengthens demand for platform-specific consumables.
Monitoring and Digital Health Devices is projected to grow fastest, at a CAGR of 19.20% during 2027 to 2033. The segment can reach users through hospitals, home-care programs and consumer channels, allowing adoption without waiting for large institutional equipment cycles. In July 2025, Aktiia received FDA clearance for the Hilo Band, the first cuffless blood-pressure monitor cleared for over-the-counter use in the United States. Such devices extend clinically relevant monitoring into everyday settings and generate continuing demand for connected applications and patient-data services.
By Technology:
- AI-Enabled Medical Devices
- Robotics-Assisted Medical Devices
- IoT / Connected Medical Devices
- Wearable Medical Devices
- Minimally Invasive Systems
- Imaging and Visualization Systems
Installed Scanner Fleets Keep Imaging and Visualization Systems Ahead at 25%
Imaging and Visualization Systems held the dominant 25.7% share in 2026. CT, MRI, ultrasound and related systems are high-value clinical assets used across emergency care, oncology, cardiology and general diagnosis. In August 2026, GE HealthCare received European certification for Photonova Spectra, its photon-counting CT system. The certification enables commercial activity in countries recognizing the CE mark and broadens access to a new generation of CT equipment.
AI-Enabled Medical Devices is projected to grow fastest, at a CAGR of 19.85% during 2027 to 2033. Unlike capital equipment, clinical software can be introduced through licences and updates across compatible installed systems. In March 2026, Philips received FDA clearance for SmartHeart, an AI-based planning tool that automates important preparation steps in cardiac MRI examinations. Such tools increase the operational value of existing imaging systems while creating a recurring software layer around the hardware.
Unlock Market Intelligence
Explore the market potential with our data-driven report
Hi-tech Medical Devices Market Regional Analysis
North America held the dominant 40.0% share of the hi-tech medical devices market in 2026. The region combines substantial hospital purchasing capacity with established diagnostic networks, high procedural volumes and relatively early adoption of robotic surgery, connected monitoring and AI-enabled clinical software. Its regulatory and reimbursement infrastructure also gives manufacturers a defined route for commercializing advanced devices. The region should retain leadership through 2033, although its established equipment base is likely to produce steadier growth than less-developed markets.
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 8.60% during 2027 to 2033. Hospital construction, diagnostic-capacity expansion and local manufacturing are increasing the number of facilities capable of purchasing advanced equipment. China, India and Southeast Asian markets also provide substantial scope for first-time installations outside major metropolitan hospitals. Regional growth will remain uneven, but suppliers offering locally manufactured or appropriately priced systems with dependable maintenance coverage should be well positioned to capture this expansion.

Hi-tech Medical Devices Market Competitive Landscape
The industry is moderately fragmented, with no single supplier holding a controlling position across device categories, regions or care settings. The five largest companies together held a combined 33% share in 2026. The top five are Johnson & Johnson, Medtronic plc, Abbott Laboratories, Stryker Corporation and Siemens Healthineers AG.
Key Companies in the Hi-tech Medical Devices Market
- Johnson & Johnson
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Siemens Healthineers AG
- GE HealthCare Technologies Inc.
- Boston Scientific Corporation
- F. Hoffmann-La Roche Ltd
- Koninklijke Philips N.V.
- Becton, Dickinson and Company
- Intuitive Surgical, Inc.
- Alcon Inc.
- Zimmer Biomet Holdings, Inc.
- Terumo Corporation
- Canon Inc.
Company Profiling
The following profiles cover the five leading manufacturers shaping product development, distribution and competitive positioning across the industry.
Johnson & Johnson: Johnson & Johnson is headquartered in New Brunswick, New Jersey, and participates through cardiovascular, orthopedic, surgical and vision technologies. In July 2026, the FDA granted De Novo authorization to its OTTAVA robotic surgical system for multiple upper-abdominal procedures. Its table-integrated arms occupy 30% to 50% less space than conventional cart and boom systems, supporting deployment in a wider range of operating rooms.
Medtronic plc: Medtronic plc is headquartered in Galway, Ireland, and supplies cardiovascular, neurological, surgical, diabetes and patient-monitoring technologies. In June 2026, the company submitted applications to expand its Hugo robotic-assisted surgery system from urology into general and gynecologic procedures in the United States, potentially allowing hospitals to use the platform across a broader range of surgical departments.
Abbott Laboratories: Abbott Laboratories is headquartered in Abbott Park, Illinois, and operates across diagnostics, cardiovascular devices and diabetes care. In August 2026, the FDA authorised its Libre Duo 10 Day system, the first wearable device to continuously monitor glucose and ketones together. The system integrates with Abbott’s Libre application and is intended to provide earlier notification when ketone levels begin to rise.
Stryker Corporation: Stryker Corporation is headquartered in Portage, Michigan, and supplies orthopedics, neurotechnology, surgical equipment and connected-care products. In September 2026, the first hip arthroscopy using its SportSuite Vision application was completed at Duke Health following FDA authorization in July. The application brings arthroscopic video, CT imaging and procedural information into an Apple Vision Pro environment.
Siemens Healthineers AG: Siemens Healthineers AG is headquartered in Forchheim, Germany, and supplies imaging, diagnostics, cancer-care and image-guided treatment systems. In September 2026, the company opened a photon-counting sensor facility in Forchheim, creating a second manufacturing source alongside its Japanese operation as demand for photon-counting CT scanners increased.
Recent Developments in the Hi-tech Medical Devices Market
- January 2026: In January 2026, Becton, Dickinson and Company (BD) received FDA clearance for the EnCor EnCompass breast biopsy and tissue removal system. The system can be used with multiple breast-imaging methods, allowing diagnostic centers to standardize biopsy procedures around one platform instead of maintaining separate systems for different imaging environments.
- January 2026: In January 2026, Intuitive Surgical, Inc. (Intuitive) received FDA clearance for the da Vinci 5 system in selected cardiac procedures, including mitral-valve repair and internal mammary artery mobilization. The expansion allows participating hospitals to use the fifth-generation robotic platform in another high-value surgical specialty.
- April 2026: In April 2026, Canon Inc. (Canon Medical) launched Ultimion in Japan, the country’s first domestically produced photon-counting CT system. The system does not require a separate chiller, which can reduce the building modifications needed when installing it in existing examination rooms.
Frequently Asked Questions
Related Report
- Market Segmentation
- Research Scope
- Research Methodology
- Definitions and Assumptions
- Executive Summary
- Global Hi-tech Medical Devices Market Policies, Regulations, and Standards
- Global Hi-tech Medical Devices Market Dynamics
- Growth Factors
- Challenges
- Trends
- Opportunities
- Global Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product Type
- Diagnostic Imaging Equipment- Market Insights and Forecast 2023-2033, USD Million
- Cardiovascular Devices- Market Insights and Forecast 2023-2033, USD Million
- In-Vitro Diagnostic Devices- Market Insights and Forecast 2023-2033, USD Million
- Surgical Equipment and Robotic Systems- Market Insights and Forecast 2023-2033, USD Million
- Orthopedic Devices- Market Insights and Forecast 2023-2033, USD Million
- Neurology Devices- Market Insights and Forecast 2023-2033, USD Million
- Ophthalmic Devices- Market Insights and Forecast 2023-2033, USD Million
- Dental Devices- Market Insights and Forecast 2023-2033, USD Million
- Diabetes Care Devices- Market Insights and Forecast 2023-2033, USD Million
- Anesthesia and Respiratory Devices- Market Insights and Forecast 2023-2033, USD Million
- Nephrology and Urology Devices- Market Insights and Forecast 2023-2033, USD Million
- ENT Devices- Market Insights and Forecast 2023-2033, USD Million
- Monitoring and Digital Health Devices- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- By Technology
- AI-Enabled Medical Devices- Market Insights and Forecast 2023-2033, USD Million
- Robotics-Assisted Medical Devices- Market Insights and Forecast 2023-2033, USD Million
- IoT / Connected Medical Devices- Market Insights and Forecast 2023-2033, USD Million
- Wearable Medical Devices- Market Insights and Forecast 2023-2033, USD Million
- Minimally Invasive Systems- Market Insights and Forecast 2023-2033, USD Million
- Imaging and Visualization Systems- Market Insights and Forecast 2023-2033, USD Million
- By Application
- Diagnosis- Market Insights and Forecast 2023-2033, USD Million
- Monitoring- Market Insights and Forecast 2023-2033, USD Million
- Therapeutics / Treatment- Market Insights and Forecast 2023-2033, USD Million
- Surgical Procedures- Market Insights and Forecast 2023-2033, USD Million
- Rehabilitation- Market Insights and Forecast 2023-2033, USD Million
- By End User
- Hospitals and Clinics- Market Insights and Forecast 2023-2033, USD Million
- Diagnostic and Imaging Centers- Market Insights and Forecast 2023-2033, USD Million
- Ambulatory Surgical Centers- Market Insights and Forecast 2023-2033, USD Million
- Research and Academic Institutes- Market Insights and Forecast 2023-2033, USD Million
- Home Care Settings- Market Insights and Forecast 2023-2033, USD Million
- By Region
- North America
- South America
- Europe
- Middle East & Africa
- Asia Pacific
- By Competitors
- Competition Characteristics
- Market Share & Analysis
- By Product Type
- Market Size & Growth Outlook
- North America Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Country
- The US
- Canada
- Mexico
- The US Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Canada Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Mexico Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Market Size & Growth Outlook
- South America Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Country
- Brazil
- Argentina
- Chile
- Rest of South America
- Brazil Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Argentina Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Chile Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Market Size & Growth Outlook
- Europe Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Country
- Germany
- The UK
- France
- Italy
- Spain
- BENELUX
- Nordics
- Rest of Europe
- Germany Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- The UK Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- France Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Italy Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Spain Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- BENELUX Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Nordics Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Market Size & Growth Outlook
- Middle East & Africa Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Country
- UAE
- Saudi Arabia
- South Africa
- Turkey
- Rest of Middle East & Africa
- UAE Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Saudi Arabia Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- South Africa Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Turkey Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Market Size & Growth Outlook
- Asia Pacific Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- By Country
- China
- India
- Japan
- South Korea
- Australia
- Southeast Asia
- Rest of Asia Pacific
- China Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- India Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- South Korea Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Australia Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Southeast Asia Hi-tech Medical Devices Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product / Device Type- Market Insights and Forecast 2023-2033, USD Million
- By Technology- Market Insights and Forecast 2023-2033, USD Million
- By Application- Market Insights and Forecast 2023-2033, USD Million
- By End User- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Market Size & Growth Outlook
- Competitive Outlook
- Company Profiles
- Johnson & Johnson
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Medtronic plc
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Abbott Laboratories
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Stryker Corporation
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Siemens Healthineers AG
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- GE HealthCare Technologies Inc.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Boston Scientific Corporation
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- F. Hoffmann-La Roche Ltd (Roche Diagnostics)
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Koninklijke Philips N.V.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Becton, Dickinson and Company
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Intuitive Surgical, Inc.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Alcon Inc.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Zimmer Biomet Holdings, Inc.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Terumo Corporation
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Canon Inc. (Canon Medical)
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Johnson & Johnson
- Company Profiles
- Disclaimer
| Segment | Sub-Segment |
|---|---|
| By Product Type |
|
| By Technology |
|
| By Application |
|
| By End User |
|
| By Region |
|
Research Methodology
This study followed a structured approach comprising four key phases to assess the size and scope of the electro-oxidation market. The process began with thorough secondary research to collect data on the target market, related markets, and broader industry context. These findings, along with preliminary assumptions and estimates, were then validated through extensive primary research involving industry experts from across the value chain. To calculate the overall market size, both top-down and bottom-up methodologies were employed. Finally, market segmentation and data triangulation techniques were applied to refine and validate segment-level estimations.
Secondary Research
The secondary research phase involved gathering data from a wide range of credible and published sources. This step helped in identifying industry trends, defining market segmentation, and understanding the market landscape and value chain.
Sources consulted during this phase included:
- Company annual reports, investor presentations, and press releases
- Industry white papers and certified publications
- Trade directories and market-recognized databases
- Articles from authoritative authors and reputable journals
- Gold and silver standard websites
Secondary research was critical in mapping out the industry's value chain and monetary flow, identifying key market segments, understanding regional variations, and tracking significant industry developments.
Other key sources:
- Financial disclosures
- Industry associations and trade bodies
- News outlets and business magazines
- Academic journals and research studies
- Paid industry databases
Primary Research
To validate secondary data and gain deeper market insights, primary research was conducted with key stakeholders across both the supply and demand sides of the market.
On the demand side, participants included decision-makers and influencers from end-user industries—such as CIOs, CTOs, and CSOs—who provided first-hand perspectives on market needs, product usage, and future expectations.
On the supply side, interviews were conducted with manufacturers, industry associations, and institutional participants to gather insights into current offerings, product pipelines, and market challenges.
Primary interviews provided critical inputs such as:
- Market size and revenue data
- Product and service breakdowns
- Market forecasts
- Regional and application-specific trends
Stakeholders consulted included:
- Leading OEM and solution providers
- Channel and distribution partners
- End users across various applications
- Independent consultants and industry specialists
Market Size Estimation and Data Triangulation
- Identifying Key Market Participants (Secondary Research)
- Goal: To identify the major players or companies in the target market. This typically involves using publicly available data sources such as industry reports, market research publications, and financial statements of companies.
- Tools: Reports from firms like Gartner, Forrester, Euromonitor, Statista, IBISWorld, and others. Public financial statements, news articles, and press releases from top market players.
- Extracting Earnings of Key Market Participants
- Goal: To estimate the earnings generated from the product or service being analyzed. This step helps in understanding the revenue potential of each market player in a specific geography.
- Methods: Earnings data can be gathered from:
- Publicly available financial reports (for listed companies).
- Interviews and primary data sources from professionals, such as Directors, VPs, SVPs, etc. This is especially useful for understanding more nuanced, internal data that isn't publicly disclosed.
- Annual reports and investor presentations of key players.
- Data Collation and Development of a Relevant Data Model
- Goal: To collate inputs from both primary and secondary sources into a structured, data-driven model for market estimation. This model will incorporate key market KPIs and any independent variables relevant to the market.
- Key KPIs: These could include:
- Market size, growth rate, and demand drivers.
- Industry-specific metrics like market share, average revenue per customer (ARPC), or average deal size.
- External variables, such as economic growth rates, inflation rates, or commodity prices, that could affect the market.
- Data Modeling: Based on this data, the market forecasts are developed for the next 5 years. A combination of trend analysis, scenario modeling, and statistical regression might be used to generate projections.
- Scenario Analysis
- Goal: To test different assumptions and validate how sensitive the market is to changes in key variables (e.g., market demand, regulatory changes, technological disruptions).
- Types of Scenarios:
- Base Case: Based on current assumptions and historical data.
- Best-Case Scenario: Assuming favorable market conditions, regulatory environments, and technological advancements.
- Worst-Case Scenario: Accounting for adverse factors, such as economic downturns, stricter regulations, or unexpected disruptions.