Japan Medical Disposables Market Report: Trends, Growth and Forecast (2027-2033)
By Product Type (Wound Management Products (Advanced Wound Care, Traditional Wound Care, Surgical Wound Care), Drug Delivery Products (Inhalers, Injection Devices, Transdermal Patches, Others), Diagnostic & Laboratory Disposables (Pipettes & Tips, Tubes & Containers, Cell Culture & Imaging Consumables, Specimen Collection & Transport Consumables, Others), Dialysis Disposables (Dialysis Catheters, Dialysis Needles, Peritoneal Dialysis Consumables), Incontinence Products (Absorbent Products, Urinary Catheters & Drainage Bags, Others), Respiratory Disposables (Respiratory Tubes, Oxygen Masks & Cannulas, Resuscitators, Others), Sterilization Supplies (Sterilization Indicators, Sterilization Packaging & Accessories), Nonwoven Disposables (Surgical Drapes, Disposable Gowns, Others), Disposable Masks (Surgical & Procedure Masks, Respirator Masks, Others), Disposable Eye Protection, Disposable Gloves (Examination Gloves, Surgical Gloves), Hand Sanitizers, Others), By Raw Material (Plastics, Nonwoven Materials, Rubber & Elastomers, Paper & Paperboard, Metals, Glass, Others), By End User (Hospitals, Home Healthcare, Outpatient & Primary Care Facilities, Others) ... Read more
|
Major Players
|
Japan Medical Disposables Market Overview
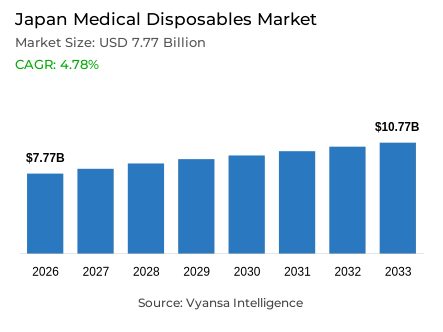
Medical disposables in Japan are single-use products consumed during examination, surgery, infusion, diagnostic testing, infection prevention, and continuing patient care. End-users span hospitals, specialty clinics, laboratories, long-term care facilities, and patients receiving treatment at home, with consumption replenished after each procedure or care episode. The Japan medical disposables market is forecast to grow at a CAGR of 4.78% between 2027 and 2033.
Key Highlights of the Japan Medical Disposables Market
- The Japan medical disposables market was valued at USD 7.77 billion in 2026, is estimated at USD 8.14 billion in 2027, and is projected to reach USD 10.77 billion by 2033.
- The market is forecast to expand at an overall 4.78% CAGR across the 2027 to 2033 forecast period.
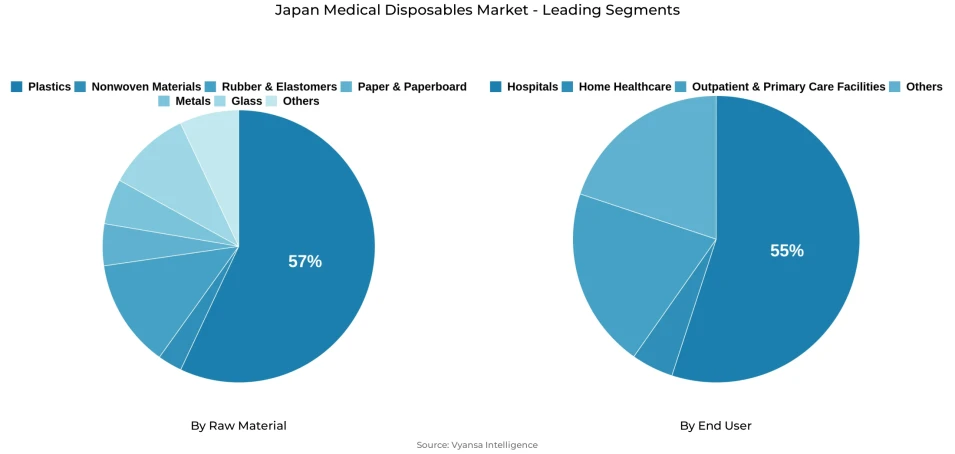
- Among raw material, plastics are the leading segment with a 57% share in 2026.
- Nonwoven materials are the fastest-growing raw material segment, expanding at an 8.34% CAGR across 2027 to 2033.
- Based on end-user, hospitals hold the dominant 55.00% share in 2026.
- Home healthcare is the fastest-growing end user segment, posting a 9.26% CAGR across 2027 to 2033.
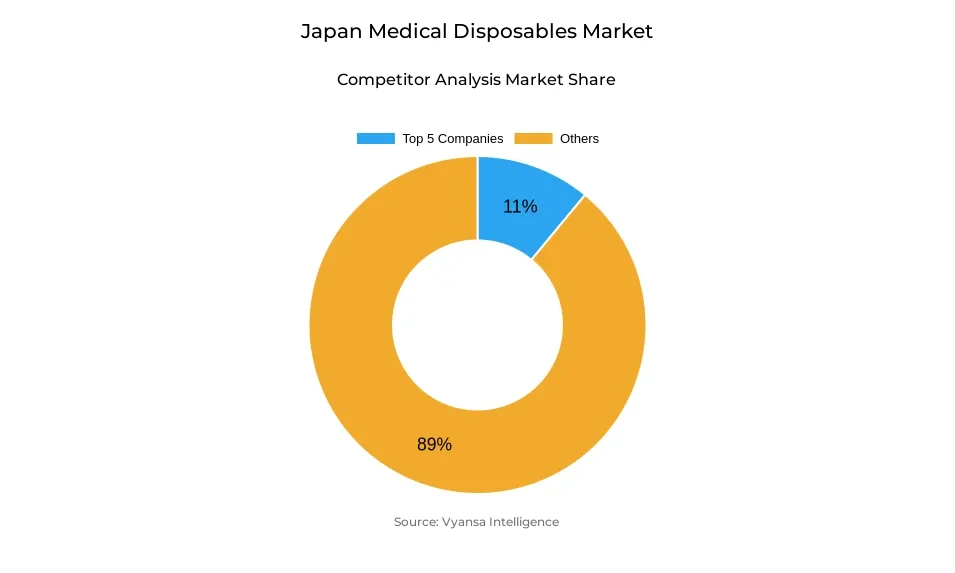
- The market is fragmented with the combined top-five company share being 11% in 2026.
Japan's medical disposables market is supported by a large and increasingly elderly healthcare population that requires repeated treatment, diagnostic testing and continuing medical assistance. As of September 2026, approximately 29% of the Japanese residents were aged 65 or older. This demographic structure provides a substantial consumption base for single-use medical products, particularly those associated with chronic disease management, infection prevention, wound care and age-related treatment.
Long-term care requirements further strengthen the underlying consumption base. According to Japan's Ministry of Health, Labor and Welfare, approximately 7.31 million people were certified as requiring nursing care or support in July 2025. These individuals generate continuing requirements for medical and personal-care consumables across institutional and non-institutional settings. Unlike medical equipment purchased through occasional capital expenditure, disposable products are replenished after individual procedures, examinations, and routine care activities, creating recurring purchasing requirements throughout the healthcare system.
Japan's established healthcare infrastructure provides another foundation for this market. The ministry's 2023 Patient Survey estimated approximately 7.28 million outpatients on an average survey day, demonstrating the substantial volume of recurring clinical interactions supported by the country's healthcare system. Simultaneously, the distribution of medical care is changing as patients increasingly receive treatment and continuing support through community facilities and home-based services. This creates requirements for disposable products suited to different purchasing channels, treatment environments, and levels of clinical supervision.
Through 2033, market development should reflect a combination of recurring clinical consumption, changing pharmaceutical logistics models and greater emphasis on operational efficiency. Suppliers that provide dependable product availability, clinically appropriate disposable formats, and solutions that reduce preparation and handling requirements can strengthen their relationships with healthcare providers.
Japan Medical Disposables Market Government Regulations
Medical Device Quality Requirements Are Strengthening Product Qualification and Market Access
Japan maintains a structured regulatory framework for medical disposables classified as medical devices. Depending on product classification, manufacturers and marketing authorization holders must complete the applicable notification, certification, or approval procedures before supplying products to the Japanese market. This creates specific market-access requirements for companies supplying regulated products such as syringes, catheters, and other clinical consumables.
Manufacturing quality is governed by Ministerial Ordinance No. 169, which establishes quality-management requirements aligned with ISO 13485. In July 2025, the Ministry of Health, Labor and Welfare updated its QMS inspection procedures, supporting consistency in how relevant authorities assess manufacturers' compliance. These requirements are particularly important for companies supplying products whose manufacturing consistency and documented quality controls are essential to clinical use.
Regulatory transparency is also developing. From fiscal 2025, Japan's Pharmaceuticals and Medical Devices Agency began preparing and publishing review summaries for certain approved improved medical devices supported by clinical evidence. Although this initiative primarily concerns qualifying higher-value devices rather than commodity disposables, it demonstrates Japan's continuing emphasis on documented clinical evaluation and regulatory transparency.
For manufacturers, compliance is therefore an important condition of market participation. Companies entering regulated disposable categories need appropriate manufacturing controls, technical documentation and product-specific authorization.
Japan Medical Disposables Market Drivers
Ageing-Related Treatment Intensity Sustains Recurring Medical Disposable Consumption
Japan's ageing population supports disposable consumption through greater treatment intensity per patient. Older patients require repeated vascular access, blood collection, wound treatment, dialysis, infusion and diagnostic testing rather than one-time clinical intervention. Each episode requires fresh sterile products, linking market demand more closely to the frequency and complexity of treatment than to the country's headline population growth.
In 2025, almost three in ten people in Japan were aged 65 or older. This demographic structure creates a large patient base requiring longer periods of chronic disease management and repeated interaction with healthcare providers. Catheters, syringes, dressings, sampling products and infusion-related disposables therefore benefit from recurring use across hospitals and continuing-care settings.
Through 2033, the strongest impact should appear in products connected to repeated treatment pathways such as dialysis, vascular access, chronic infusion and wound management. Ageing also increases the value of products that reduce handling time and complication risk because healthcare staff must manage more complex care episodes without a proportional increase in available labor.
Japan Medical Disposables Market Challenges
Reimbursement Pressure Constrains Revenue Growth for Higher-Value Disposables
Higher clinical consumption does not automatically translate into equivalent supplier revenue growth because many specialized disposable products operate within Japan's reimbursement system. Hospitals must consider what can be recovered through insured treatment when evaluating advanced catheters and other procedural materials. This places a practical limit on the amount manufacturers can charge even when products incorporate additional technology or functionality.
Japan revised reimbursement treatment for specialized medical materials during 2026, reinforcing the need for manufacturers to demonstrate why an advanced disposable deserves stronger clinical and economic recognition. Products with only incremental specification differences face greater difficulty defending a premium than those that clearly improve treatment, safety or workflow.
This creates two different competitive responses. Commodity suppliers need stronger manufacturing efficiency, while technology-led suppliers need clinical advantages that hospitals can translate into measurable value. Reimbursement pressure therefore limits unrestricted unit-price expansion but simultaneously directs spending toward products that can reduce staff workload, simplify procedures or improve patient management.
Japan Medical Disposables Recent Trends
Procedure-Specific Disposable Systems Are Reducing Hospital Preparation Work
Hospital procurement is moving beyond separately assembled disposable components toward procedure-specific configurations designed around the sequence of clinical work. Traditionally, nurses gather drapes, syringes, sponges and other materials individually before a procedure. Customized kits transfer part of this preparation to the supplier and provide hospitals with a repeatable set of sterile components for a defined surgical workflow.
HOGY Medical provides one of the clearest examples. Its Premium Surgical Kit business can select components from approximately 20,000 items and configure them around individual procedures. In a joint-replacement case highlighted in its 2025 reporting, material preparation time declined from roughly 69 minutes to about 10 minutes. HOGY also manufactures more than 26,000 customized kit configurations annually, showing that procedure-specific supply is already established at commercial scale.
This shifts purchasing away from evaluating only the cost of individual disposable components. Hospitals can justify higher-value kits when reduced preparation time, fewer missing items and more standardized workflows release clinical staff for patient-facing activities. Procedure-specific disposables therefore gain value through operating efficiency rather than simply product bundling
AI and Smart Manufacturing Are Improving Disposable Production Efficiency and Quality Consistency
Medical-disposable manufacturing in Japan is moving toward more automated and digitally controlled production as suppliers look to maintain high-volume output with tighter quality requirements and limited labor availability. AI-based production planning, automated inspection, sensors and connected factory systems allow manufacturers to monitor processes more continuously, reduce manual intervention and identify production variation earlier. This is particularly relevant for syringes, catheters, needles and other disposables where consistent quality must be maintained across large production volumes.
Terumo reported in 2025 that it was using AI for demand forecasting while expanding smart-factory initiatives based on sensors, connected production equipment and automated manufacturing. The company is also using digital systems to improve inventory monitoring and production planning across thousands of medical products. Nipro is moving in the same direction, with its current management plan specifically targeting greater production automation and ultimately fully automated inspection across its product portfolio.
The market impact is lower dependence on repetitive manual inspection, better production consistency and greater flexibility when demand shifts between disposable categories. Automated manufacturing also helps larger suppliers absorb reimbursement and procurement pressure without compromising quality. Through 2033, AI-enabled planning, machine-level monitoring and automated inspection should therefore become more important competitive capabilities for medical-disposable manufacturers seeking to combine large-scale output with dependable supply and traceability.
Japan Medical Disposables Market Future Opportunities
Expanding Catheter-Based Care Creates a Higher-Value Single-Use Product Opportunity
Catheter-based treatment represents the strongest product opportunity because it combines recurring sterile consumption with continued expansion of minimally invasive and chronic-care procedures. Cardiovascular intervention, dialysis, vascular access, urinary management and infusion all create demand for catheter-related products, while advanced functionality allows manufacturers to compete beyond basic unit price.
Terumo reinforced this direction in May 2026 with the Japanese launch of TR Band Distal for distal radial procedures. The product focuses on simplifying post-procedure hemostasis while improving visibility and patient comfort, illustrating how value is increasingly built around the wider catheter procedure rather than the catheter alone.
The opportunity favors manufacturers already serving vascular access, dialysis and interventional departments because they can extend into adjacent disposable products through established clinical relationships. Advanced catheter systems, access products and post-procedure devices can therefore capture a greater portion of incremental market value than standardized commodity consumables.
Unlock Market Intelligence
Explore the market potential with our data-driven report
Japan Medical Disposables Market Segmentation Analysis
By Raw Material
- Plastics
- Rubber & Elastomers
- Nonwoven Materials
- Paper & Cellulose
- Metals
- Glass
- Others
Plastics Lead Raw Material Demand While Nonwoven Materials Records the Fastest Growth
Plastics dominate Japan's medical disposables market by raw material, accounting for approximately 57% of the market share in 2026. Their extensive utilization in syringes, catheters, infusion components, specimen containers, and other single-use medical products supports demand across hospitals and healthcare facilities. Their cost-effectiveness, manufacturing flexibility, compatibility with sterilization processes, and suitability for high-volume production reinforce their widespread adoption. Additionally, the growing demand for reliable medical consumables and the availability of specialized medical-grade polymers continue to support the segment's dominant position.
Nonwoven materials are projected to be the fastest-growing raw material segment in Japan's medical disposables market, registering a CAGR of 8.34% during 2027–2033. Their increasing utilization in surgical drapes, gowns, sterilization products, and procedure-specific medical consumables is supporting market expansion. Growing emphasis on infection prevention, disposable surgical products, and advanced barrier protection is encouraging manufacturers to develop specialized nonwoven materials. Domestic manufacturers, including HOGY Medical, are incorporating these materials into surgical products and procedure kits, supporting broader adoption across healthcare facilities.
By End User
- Hospitals
- General & Specialty Clinics
- Diagnostic & Laboratory Facilities
- Long-Term Care Facilities
- Home Healthcare
- Other Healthcare Settings
Hospitals Remain the Dominant End User but Home Healthcare Records the Fastest Growth
Hospitals hold a 55.00% share in 2026 because surgery, emergency treatment, catheterization, dialysis, intensive care and inpatient services consume several disposable categories during the same patient episode. One procedure can require gloves, syringes, drapes, catheters, dressings and sampling products simultaneously, giving hospitals considerably greater disposable intensity than lower-acuity settings. Hospitals are also moving toward products that reduce staff workload. HOGY MEDICAL's large customized surgical-kit business demonstrates how acute-care procurement can shift toward higher-value configurations when they reduce preparation requirements and improve procedure standardization.
Home Healthcare grows fastest at a 9.26% CAGR during 2027 to 2033 because chronic treatment is expanding from a much smaller existing consumption base. Hospitals remain the primary clients, while home settings add new recurring demand for wound care, urinary management, monitoring and other products suited to continuing treatment.
Unlock Market Intelligence
Explore the market potential with our data-driven report
Japan Medical Disposables Market Competitive Landscape
The Japan medical disposables market is fragmented with the combined share of 11%. The top companies in the market are Terumo Corporation, Nipro Corporation, JMS Co., Ltd., HOGY MEDICAL Co., Ltd. and Kawamoto Corporation.
Key Companies in the Japan Medical Disposables Market
- Terumo Corporation
- Nipro Corporation
- JMS Co., Ltd.
- HOGY MEDICAL Co., Ltd.
- Kawamoto Corporation
- Japan Becton Dickinson Company, Ltd.
- Cardinal Health Japan
- Smith & Nephew Japan
- B. Braun Aesculap Japan Co., Ltd.
- Medline Japan
- TOP Corporation
- Asahi Kasei Medical Co., Ltd.
Recent Developments in the Japan Medical Disposables Market
- In July 2026, Terumo Corporation expanded a voluntary recall of specified Relay Pro Thoracic Stent-Graft System models after first initiating the recall in Japan on June 1, 2026. Approximately 7,000 affected units had been distributed globally between May 2024 and March 2026. The action highlights the qualification and post-market surveillance burden attached to technically complex disposable and single-use interventional systems, reinforcing procurement emphasis on documented device reliability and supplier quality management.
- In April 2026, JMS Co., Ltd. issued specification updates covering its Safety Winged Blood Collection Set, Safety SV Set and JMS Scalp Vein Set, followed by additional portfolio updates during the year covering gloves, tubing and infusion-related products. These changes show that competition in established disposable categories involves continued specification management and safety refinement rather than relying only on entirely new product launches.
Frequently Asked Questions
Related Report
- Market Segmentation
- Research Scope
- Research Methodology
- Definitions and Assumptions
- Executive Summary
- Japan Medical Disposables Market Policies, Regulations, and Standards
- Japan Medical Disposables Market Dynamics
- Growth Factors
- Challenges
- Trends
- Opportunities
- Japan Medical Disposables Market Statistics, 2023-2033F
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Product Type
- Wound Management Products- Market Insights and Forecast 2023-2033, USD Million
- Advanced Wound Care- Market Insights and Forecast 2023-2033, USD Million
- Traditional Wound Care- Market Insights and Forecast 2023-2033, USD Million
- Surgical Wound Care- Market Insights and Forecast 2023-2033, USD Million
- Drug Delivery Products- Market Insights and Forecast 2023-2033, USD Million
- Inhalers- Market Insights and Forecast 2023-2033, USD Million
- Injection Devices- Market Insights and Forecast 2023-2033, USD Million
- Transdermal Patches- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- Diagnostic & Laboratory Disposables- Market Insights and Forecast 2023-2033, USD Million
- Pipettes & Tips- Market Insights and Forecast 2023-2033, USD Million
- Tubes & Containers- Market Insights and Forecast 2023-2033, USD Million
- Cell Culture & Imaging Consumables- Market Insights and Forecast 2023-2033, USD Million
- Specimen Collection & Transport Consumables- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- Dialysis Disposables- Market Insights and Forecast 2023-2033, USD Million
- Dialysis Catheters- Market Insights and Forecast 2023-2033, USD Million
- Dialysis Needles- Market Insights and Forecast 2023-2033, USD Million
- Peritoneal Dialysis Consumables- Market Insights and Forecast 2023-2033, USD Million
- Incontinence Products- Market Insights and Forecast 2023-2033, USD Million
- Absorbent Products- Market Insights and Forecast 2023-2033, USD Million
- Urinary Catheters & Drainage Bags- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- Respiratory Disposables- Market Insights and Forecast 2023-2033, USD Million
- Respiratory Tubes- Market Insights and Forecast 2023-2033, USD Million
- Oxygen Masks & Cannulas- Market Insights and Forecast 2023-2033, USD Million
- Resuscitators- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- Sterilization Supplies- Market Insights and Forecast 2023-2033, USD Million
- Sterilization Indicators- Market Insights and Forecast 2023-2033, USD Million
- Sterilization Packaging & Accessories- Market Insights and Forecast 2023-2033, USD Million
- Nonwoven Disposables- Market Insights and Forecast 2023-2033, USD Million
- Surgical Drapes- Market Insights and Forecast 2023-2033, USD Million
- Disposable Gowns- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- Disposable Masks- Market Insights and Forecast 2023-2033, USD Million
- Surgical & Procedure Masks- Market Insights and Forecast 2023-2033, USD Million
- Respirator Masks- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- Disposable Eye Protection- Market Insights and Forecast 2023-2033, USD Million
- Disposable Gloves- Market Insights and Forecast 2023-2033, USD Million
- Examination Gloves- Market Insights and Forecast 2023-2033, USD Million
- Surgical Gloves- Market Insights and Forecast 2023-2033, USD Million
- Hand Sanitizers- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- Wound Management Products- Market Insights and Forecast 2023-2033, USD Million
- By Raw Material
- Plastics- Market Insights and Forecast 2023-2033, USD Million
- Nonwoven Materials- Market Insights and Forecast 2023-2033, USD Million
- Rubber & Elastomers- Market Insights and Forecast 2023-2033, USD Million
- Paper & Paperboard- Market Insights and Forecast 2023-2033, USD Million
- Metals- Market Insights and Forecast 2023-2033, USD Million
- Glass- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- By End User
- Hospitals- Market Insights and Forecast 2023-2033, USD Million
- Home Healthcare- Market Insights and Forecast 2023-2033, USD Million
- Outpatient & Primary Care Facilities- Market Insights and Forecast 2023-2033, USD Million
- Others- Market Insights and Forecast 2023-2033, USD Million
- By Competitors
- Competition Characteristics
- Market Share & Analysis
- By Product Type
- Market Size & Growth Outlook
- Japan Wound Management Disposables Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Drug Delivery Products Disposables Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Diagnostic & Laboratory Disposables Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Dialysis Disposables Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Incontinence Products Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Respiratory Disposables Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Sterilization Supplies Disposables Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Nonwoven Disposables Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Disposable Masks Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Disposable Eye Protection Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Disposable Gloves Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Hand Sanitizers Disposables Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Japan Others Market Statistics, 2023-2033
- Market Size & Growth Outlook
- By Revenues in USD Million
- Market Segmentation & Growth Outlook
- By Raw Material- Market Insights and Forecast 2023-2033, USD Million
- By End Use- Market Insights and Forecast 2023-2033, USD Million
- Market Size & Growth Outlook
- Competitive Outlook
- Company Profiles
- Terumo Corporation
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- NIPRO CORPORATION
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- HOGY MEDICAL CO., LTD.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- JMS CO., LTD.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Johnson & Johnson K.K. Medical Company
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- TOP Corporation
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Medikit Co., Ltd.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Nippon Becton Dickinson Company, Ltd.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Cardinal Health K.K.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Medline Japan G.K.
- Business Description
- Product Portfolio
- Collaborations & Alliances
- Recent Developments
- Financial Details
- Others
- Terumo Corporation
- Company Profiles
- Disclaimer
| Segment | Sub-Segment |
|---|---|
| By Product Type |
|
| By Raw Material |
|
| By End User |
|
Research Methodology
This study followed a structured approach comprising four key phases to assess the size and scope of the electro-oxidation market. The process began with thorough secondary research to collect data on the target market, related markets, and broader industry context. These findings, along with preliminary assumptions and estimates, were then validated through extensive primary research involving industry experts from across the value chain. To calculate the overall market size, both top-down and bottom-up methodologies were employed. Finally, market segmentation and data triangulation techniques were applied to refine and validate segment-level estimations.
Secondary Research
The secondary research phase involved gathering data from a wide range of credible and published sources. This step helped in identifying industry trends, defining market segmentation, and understanding the market landscape and value chain.
Sources consulted during this phase included:
- Company annual reports, investor presentations, and press releases
- Industry white papers and certified publications
- Trade directories and market-recognized databases
- Articles from authoritative authors and reputable journals
- Gold and silver standard websites
Secondary research was critical in mapping out the industry's value chain and monetary flow, identifying key market segments, understanding regional variations, and tracking significant industry developments.
Other key sources:
- Financial disclosures
- Industry associations and trade bodies
- News outlets and business magazines
- Academic journals and research studies
- Paid industry databases
Primary Research
To validate secondary data and gain deeper market insights, primary research was conducted with key stakeholders across both the supply and demand sides of the market.
On the demand side, participants included decision-makers and influencers from end-user industries—such as CIOs, CTOs, and CSOs—who provided first-hand perspectives on market needs, product usage, and future expectations.
On the supply side, interviews were conducted with manufacturers, industry associations, and institutional participants to gather insights into current offerings, product pipelines, and market challenges.
Primary interviews provided critical inputs such as:
- Market size and revenue data
- Product and service breakdowns
- Market forecasts
- Regional and application-specific trends
Stakeholders consulted included:
- Leading OEM and solution providers
- Channel and distribution partners
- End users across various applications
- Independent consultants and industry specialists
Market Size Estimation and Data Triangulation
- Identifying Key Market Participants (Secondary Research)
- Goal: To identify the major players or companies in the target market. This typically involves using publicly available data sources such as industry reports, market research publications, and financial statements of companies.
- Tools: Reports from firms like Gartner, Forrester, Euromonitor, Statista, IBISWorld, and others. Public financial statements, news articles, and press releases from top market players.
- Extracting Earnings of Key Market Participants
- Goal: To estimate the earnings generated from the product or service being analyzed. This step helps in understanding the revenue potential of each market player in a specific geography.
- Methods: Earnings data can be gathered from:
- Publicly available financial reports (for listed companies).
- Interviews and primary data sources from professionals, such as Directors, VPs, SVPs, etc. This is especially useful for understanding more nuanced, internal data that isn't publicly disclosed.
- Annual reports and investor presentations of key players.
- Data Collation and Development of a Relevant Data Model
- Goal: To collate inputs from both primary and secondary sources into a structured, data-driven model for market estimation. This model will incorporate key market KPIs and any independent variables relevant to the market.
- Key KPIs: These could include:
- Market size, growth rate, and demand drivers.
- Industry-specific metrics like market share, average revenue per customer (ARPC), or average deal size.
- External variables, such as economic growth rates, inflation rates, or commodity prices, that could affect the market.
- Data Modeling: Based on this data, the market forecasts are developed for the next 5 years. A combination of trend analysis, scenario modeling, and statistical regression might be used to generate projections.
- Scenario Analysis
- Goal: To test different assumptions and validate how sensitive the market is to changes in key variables (e.g., market demand, regulatory changes, technological disruptions).
- Types of Scenarios:
- Base Case: Based on current assumptions and historical data.
- Best-Case Scenario: Assuming favorable market conditions, regulatory environments, and technological advancements.
- Worst-Case Scenario: Accounting for adverse factors, such as economic downturns, stricter regulations, or unexpected disruptions.